How do I get pre-approved for a mortgage and when should I do it?
Getting pre-approved means a lender reviews your income, assets, credit, and debts, then issues a letter stating how much they're willing to lend you. You should do this before you start seriously looking at homes. A pre-approval letter shows sellers you're a qualified buyer, which is essential in any competitive situation. The process usually takes a few days and requires pay stubs, tax returns, bank statements, and permission to pull your credit. Pre-approval is different from pre-qualification, which is just an estimate. Rates and loan programs change, so it's smart to connect with a lender early. The specifics depend on your situation and a licensed lender should confirm what you qualify for. Jon can connect you with one.
Specifics depend on your situation and should be confirmed with a licensed lender. Jon can connect you with one: text (623) 826-0888.
More on credit and pre-approval
- What credit score do I need to buy a house?
- What is the difference between pre-qualified and pre-approved?
- How can I raise my credit score fast before buying?
- What documents do I need for a mortgage pre-approval?
- Can I buy a house with bad credit or after a bankruptcy?
- What happens if my job changes while I am under contract?
Meet Jon Hegreness
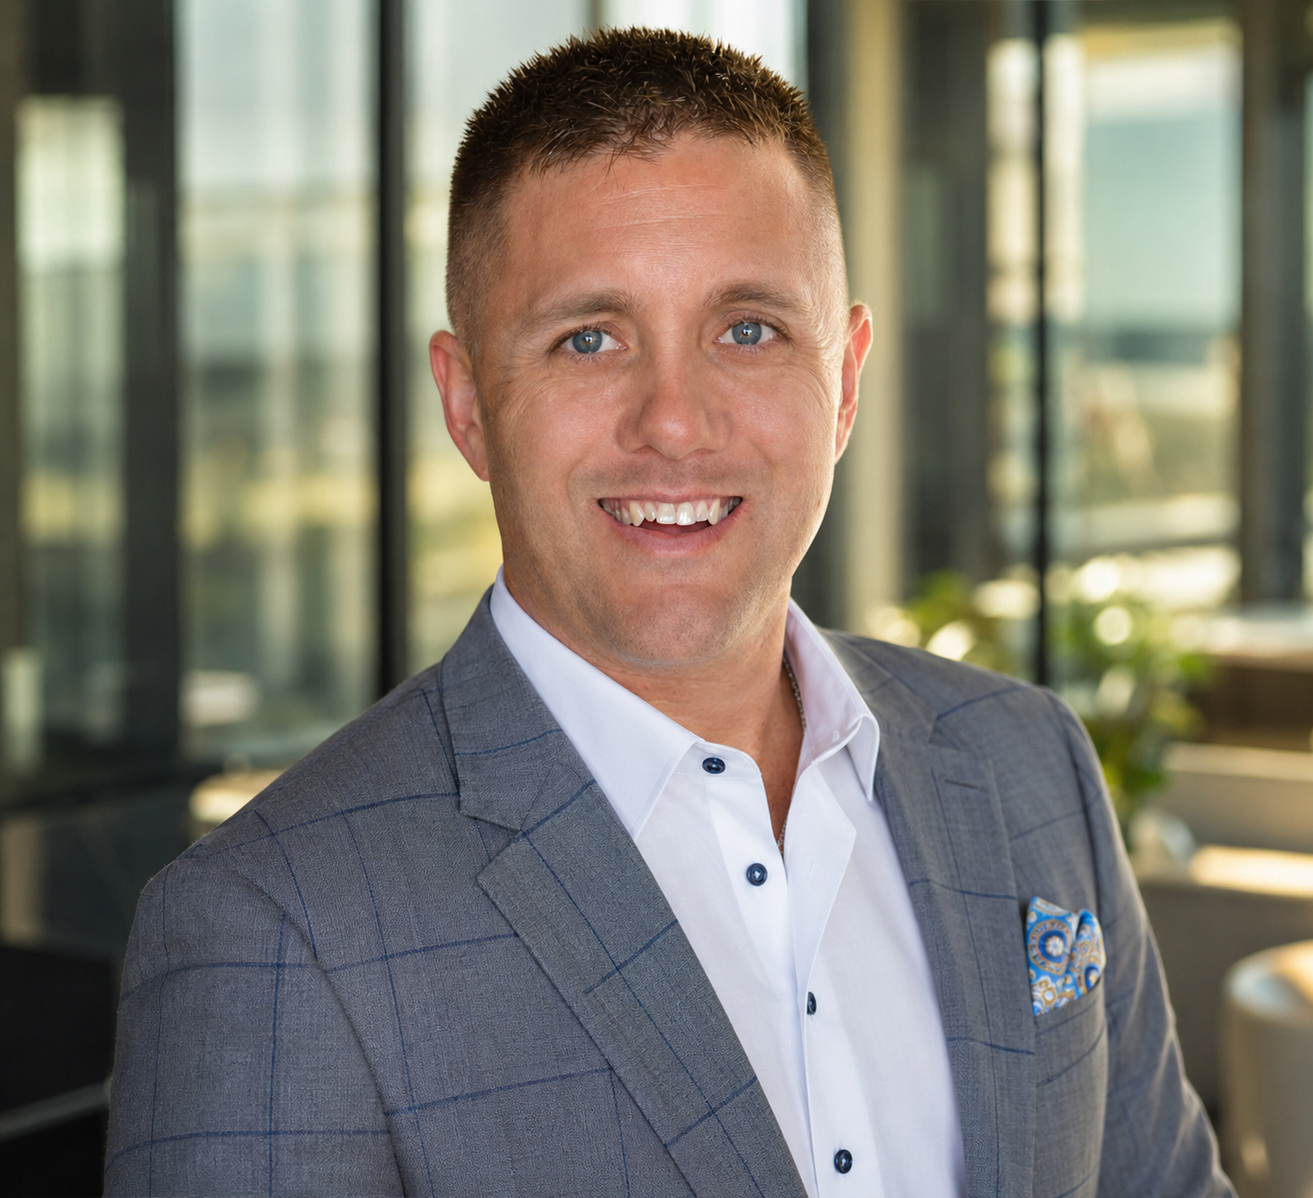
Jon Hegreness
REALTOR / Associate Broker · Howe Realty
AZ License BR540940000
Full-time Phoenix North Valley REALTOR and Associate Broker with 24 years in Arizona residential real estate. A negotiator and problem solver who works the way you would want a friend in the business to work: direct, on your side, and steady through the parts that get complicated.